MINDSET & SEASONS
My Experience With CrowdHealth: An RN’s Honest Take
September 26, 2026·6 min read
Mindset & Seasons, Health Sovereignty, Wild Roots Blog
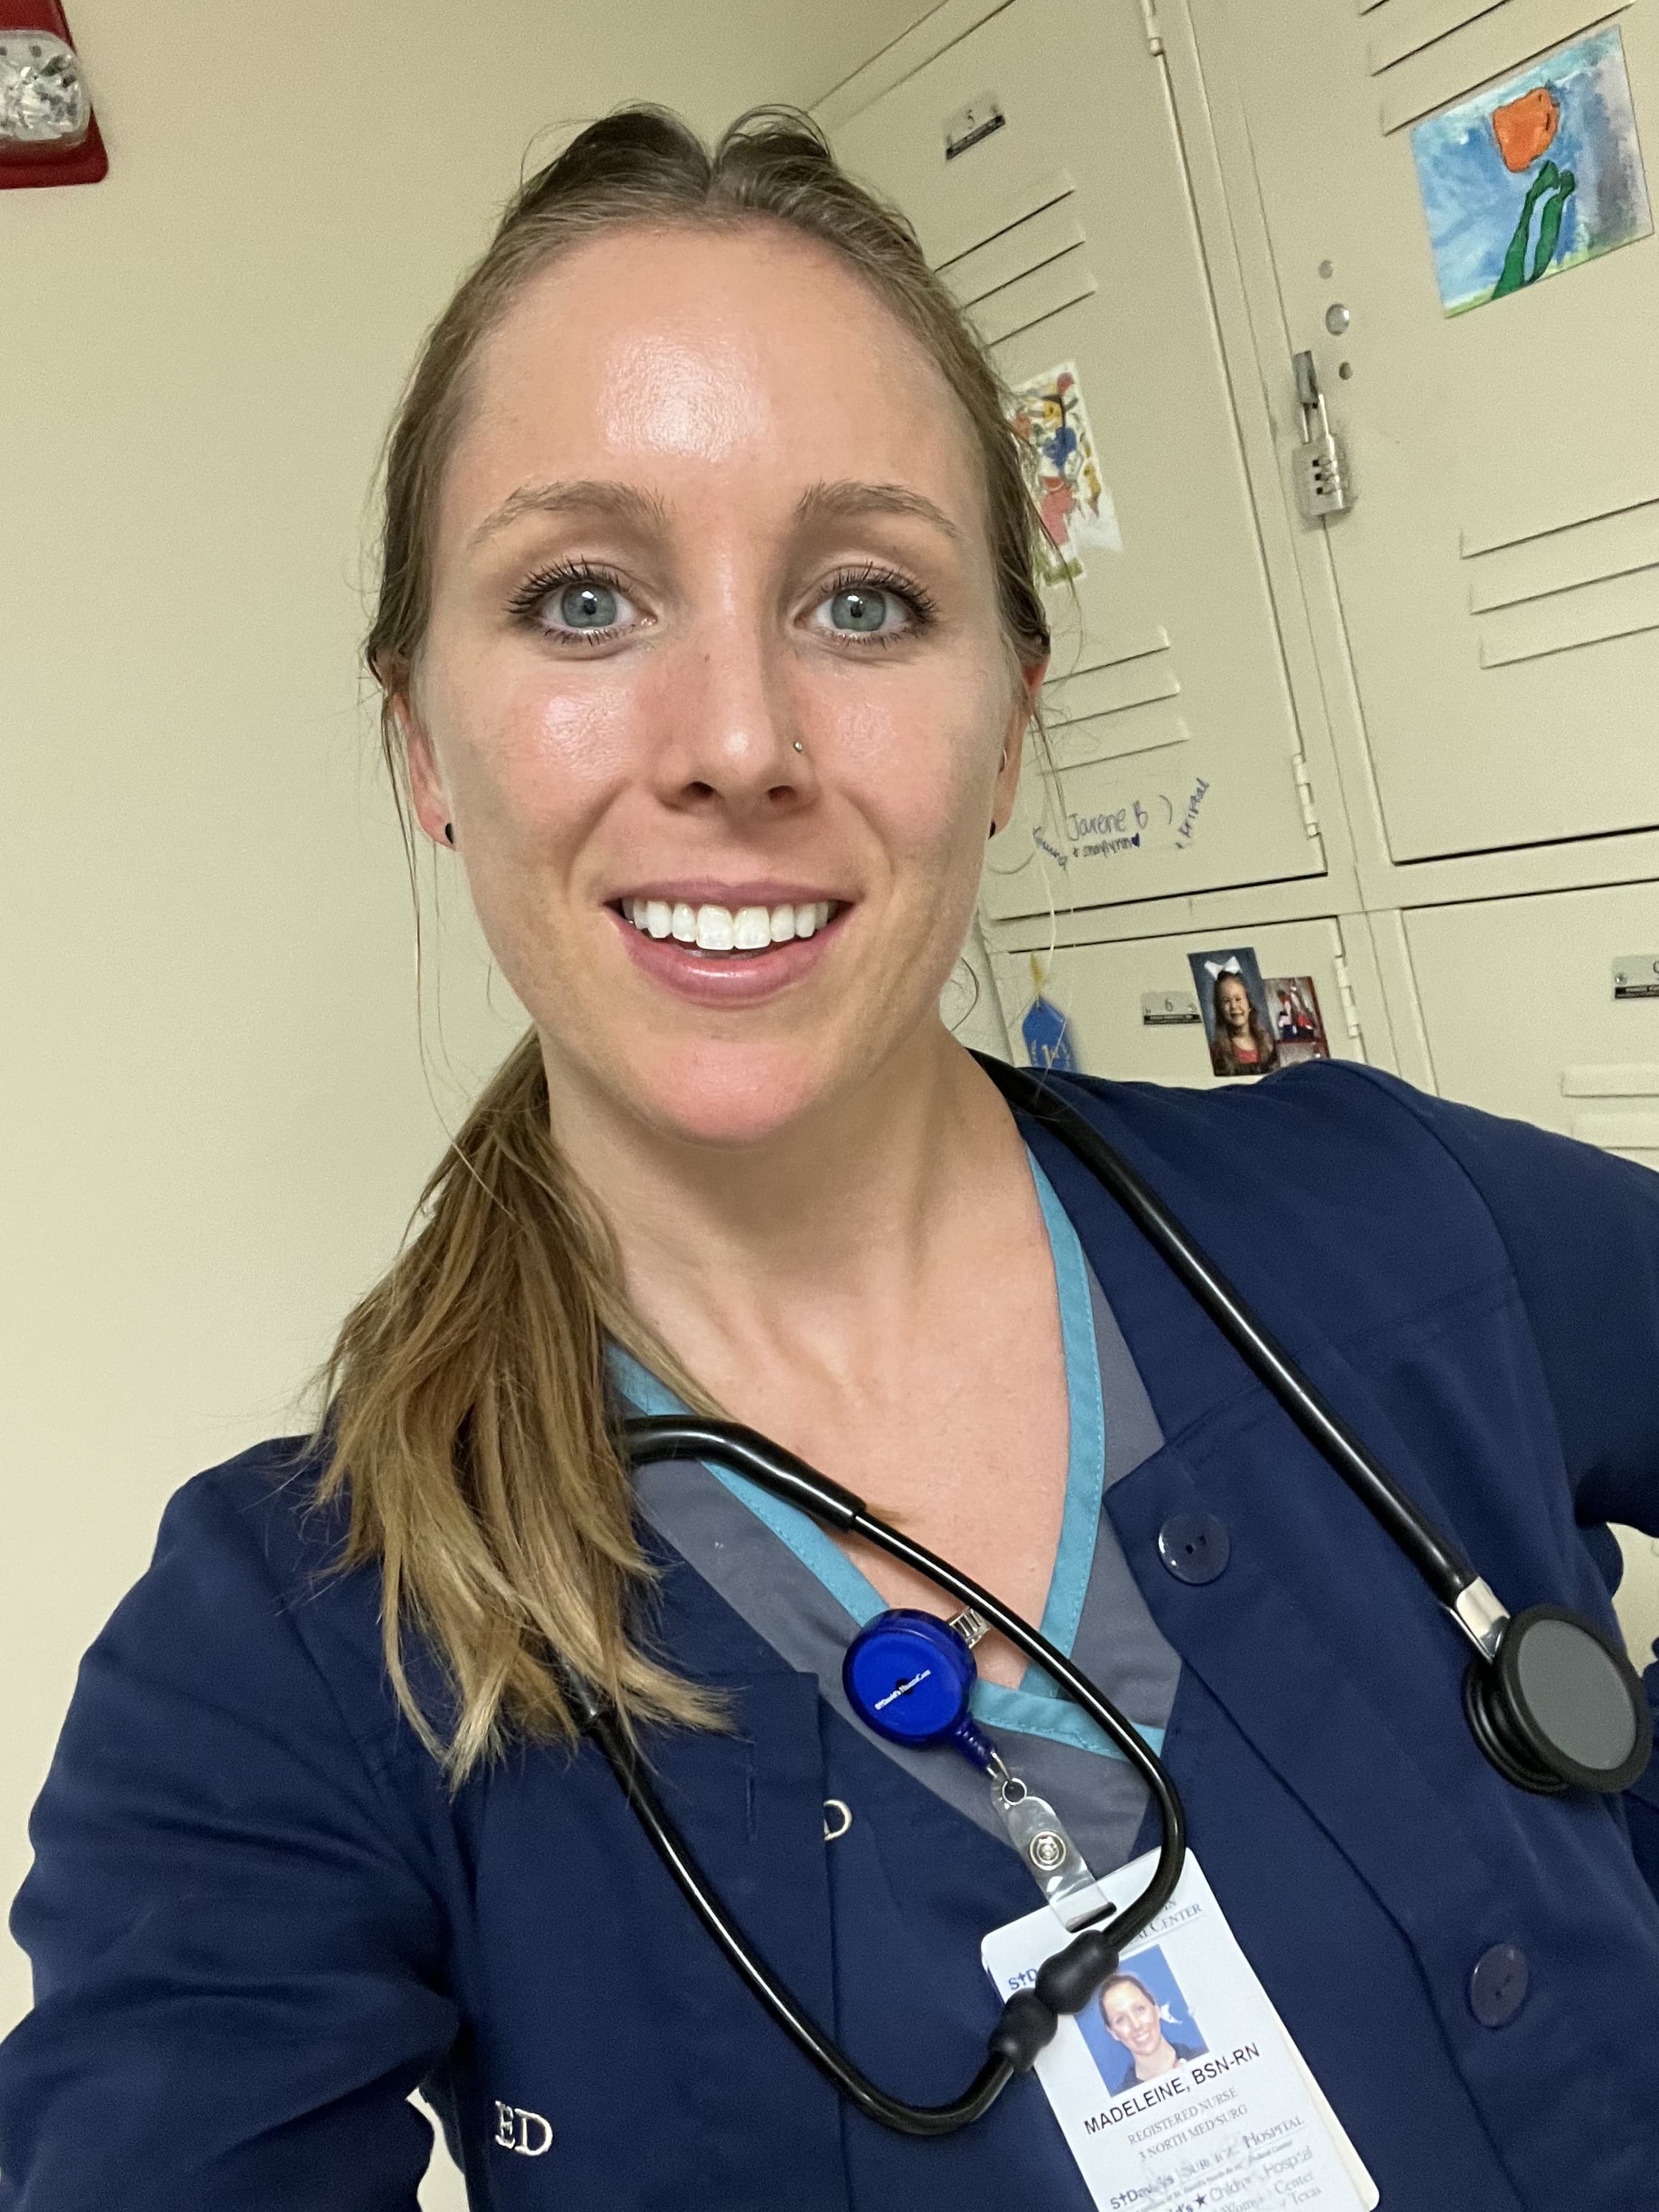
By Madeleine Gray, RN · Wild Roots Blog · Published September 26, 2026
A health share is not traditional insurance. It’s an alternative where members pay into a shared fund that covers each other’s medical needs, with lower monthly costs and real trade-offs worth knowing before you switch.
If you would’ve told me five or ten years ago that I wouldn’t have health insurance at this point, I would’ve thought you were crazy. Back then I was deep in healthcare, supporting all the causes, deep in my role as an inpatient RN, following all the rules... and I don’t mean orders, because of course I follow orders. I mean the unspoken rules. Do not question the doctor. Do as you’re told. Fall in line. Take the pill. The list goes on.
I say that because I think all of these things go together. Once your mind opens to new options and new possibilities, you keep going down that rabbit hole, and it goes on and on when it comes to finding new ways to be sovereign in your own health and well-being. One thing I’m genuinely grateful for is learning about health shares.
What is a health share, you ask? Glad you did, because I’ll tell you. It’s an alternative to traditional health insurance, where people pay into a fund that helps support other members in their time of need. There’s usually a small membership fee; for CrowdHealth, mine started around $50, maybe $99 now, and now that I have a family it’s $150 for us.
One honest thing worth knowing before I go further: a health share is not insurance. And I actually think that’s a good thing. It’s not regulated the same way, and the organization isn’t legally required to pay a bill the way an insurer is. Here’s what that looks like in practice, though: CrowdHealth is upfront about what they won’t cover, and if something reasonable comes up, something that genuinely makes sense to be shared, you can request a review. They’re not trying to screw you out of care you actually need. Traditional insurance will. I’ve seen it happen, more than once, working inpatient and dealing with insurance directly: people denied life-saving treatment over a technicality, while getting charged out the wazoo for the basic things that let a person live a decent life.
Here’s something else I saw firsthand from the inside. A lot of what gets billed to insurance is inflated well beyond what care actually costs; hospitals and providers often bill at insurance-only rates, far higher than anyone would ever pay in cash, and insurance companies negotiate their payouts off of that inflated number. It’s a system built on markup and negotiation, not on what things are actually worth. That vagueness is exactly what I don’t get with a health share. I can see what I’m paying and what it’s actually going toward.
I think every single person reading this can relate to their own experience with traditional health insurance on some level. Here’s a detail that tends to surprise people: even when I worked directly for a hospital, the kind of job you’d assume comes with close to full coverage, that wasn’t my experience. I paid around $300 a month for myself alone, as a completely healthy person with basically no history; wellness checks, dental cleanings, a well-woman exam, one old elective hip surgery, some therapy in my early twenties for anxiety. That was it. And my actual coverage came out to less than 40 percent on real claims. You’d think working inside the system would protect you from it. It didn’t.
When I moved back to Austin permanently and switched to a per diem nursing job... meaning I work as needed, no set schedule, I pick my hours as long as there are shifts available, and in the float pool there always were... it was around that time I was debt free and looking at my expenses. I was still paying that same $300 a month, for basically no health history, and it was still the cheapest option available to me as a single, healthy, independent person. Crazy, right?
I wish I could remember exactly who told me about health shares. Probably Ryan, my partner. I did a little research and came across CrowdHealth, started right here in Austin. Small and cheap at the time. I’ve stayed with them ever since, because my experience has been genuinely great.
So here’s how it actually works. You pay a membership fee, somewhere between $50 and $150 depending on your household. Then there’s a second, variable fee that caps at a certain amount... for my family, I believe that caps around $150, so at most I’m paying $300 total a month. Worth noting: pricing structures change, so don’t take my numbers as gospel; check their current rates directly.
That second fee goes directly toward someone in need, and your bill actually tells you what for; pregnancy, illness, surgery. Wellness visits are covered. For anything else, you have a deductible, just like traditional insurance, standard at $500. The one exception is pregnancy, where my plan’s deductible was $2,500. In the scheme of what pregnancy can actually cost, that’s nothing.
My own experience was a good example of this. I paid out of pocket for my midwife during pregnancy, the $2,500 in cash, and everything after that was covered. I wasn’t planning on an expensive birth; I was doing a home birth. But I ended up transferring to the hospital for two nights, and the bill was $28,000. I paid roughly $1,500 to $2,000 total.
One caveat: any expense that’s for the baby specifically, the pediatrician, newborn testing, has to run under the baby as a new member of the family. That’s the real reason I owed a bit afterward; otherwise I wouldn’t have owed anything at all, since I’d already met my deductible before any of it happened.
I’m sharing all of this for anyone who questions whether this is legit, or whether it would actually help them. Being in healthcare, I was genuinely scared to leave traditional insurance, because the industry makes you feel like they’re your only real option for full coverage. But here’s what I can tell you from the other side: as an inpatient nurse, I spent plenty of time on the phone with insurance companies myself, and I’ve seen firsthand how much they can fail people.
A health share is direct. It’s either something they can share and will, or it isn’t, and if it’s genuinely unclear, you can call and explain what it’s for and why you think it should be covered, and a real person actually listens. It won’t cover everything the way a comprehensive insurance plan might, and that discretion is real; that’s the tradeoff for what you’re saving. But in my experience, it has been fair, and it has been human, in a way traditional insurance never was for me.
Lastly, they don’t just help you in a time of need; they encourage the community to grow by giving something back to the people who help it grow. When you refer a friend or family member, they get a discount on their first three months, and you get a kickback as the person who referred them. It’s a win-win, something traditional insurance would never offer.
And because I want to be upfront about it: yes, that means I make something when you sign up through my link. I wouldn’t be sharing this if I didn’t genuinely believe in it and use it myself, five years and counting. If you want to try it, here’s my code: QZ4K0P, or use my link below: joincrowdhealth.com. Share the love, help people save some money, and escape the matrix.
- Madeleine
Holistic RN · Mama · @the_holistic_momma
FAQ
Is a health share the same as health insurance? No. A health share isn’t legally required to pay a claim the way an insurer is, and it isn’t regulated the same way. Members pay into a shared fund and requests are reviewed individually rather than guaranteed.
What does CrowdHealth actually cost per month? A membership fee, roughly $50 to $150 depending on household size, plus a second fee that caps at a set amount. For Madeleine’s family that totals around $300 a month, though pricing changes, so check current rates directly.
Does a health share cover pregnancy and birth? Yes, with a separate deductible for pregnancy ($2,500 on Madeleine’s plan). After that, most costs are shared, which is how a $28,000 hospital transfer ended up costing her about $2,000 out of pocket.
What happens if a health share won’t cover something? You can request a review and talk to a real person about why an expense should be shared. There’s no legal guarantee of payment, which is the real tradeoff for the lower monthly cost.
Is CrowdHealth legitimate? Madeleine has used it for five years, including through a home birth transfer, and says it has come through every time it mattered. She discloses that she earns a referral credit if you sign up through her link.
Want to go deeper?
If something here landed, we can talk it through — slowly, and on your terms.
Book a Free Consult